The shares of the AK ALROSA (PAO) remain the last major asset in property of the Republic of Sakha (Yakutia) that is why it is necessary to retain the state control over the company. The practical experience of the recent years has shown that it is the government support that is able to back up the diamond industry and avoid a sharp decline in the periods of economic instability and crisis in the global economy as the main component of a diamond price and diamond processing is formed on the luxury market.
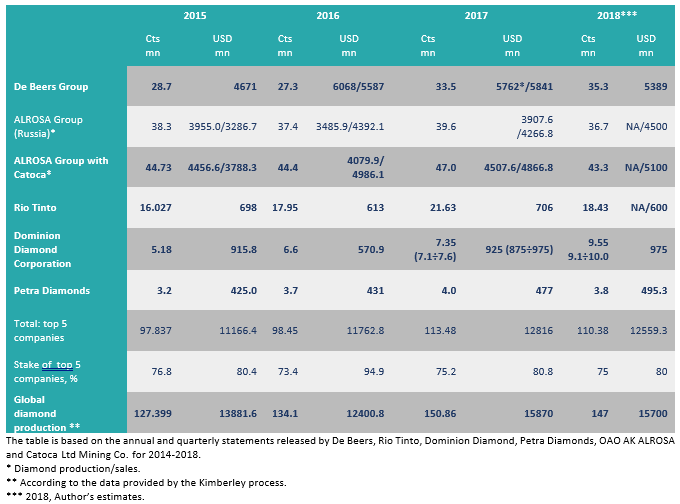
The ALROSA Group is a world leader in the diamond production by volume and outperforms De Beers by 4%, but as for diamond sales, it is almost 20% behind De Beers. However, the ALROSA Group and Catoca Ltd Mining Co. taken together exceed De Beers by 23% as for their diamond output and they sell just 5.7% less rough diamonds than De Beers. That is, as for the rough diamond sales, the ALROSA Group is almost equal to the De Beers Group (Table 1).
Table 1
World’s largest diamond miners, 2015-2018
Round 1, IPO carried out by ALROSA
The ALROSA’s shares privatization after the company (ZAO) went public (OAO, and later PAO) has gone through two stages already. As a result of long negotiations and discussions, in mid-2013, the government of the Russian Federation took a compromise decision on retaining the state control after the privatization of the ALROSA’s shares (the governments of Russia and the Republic own 25%+1 share each). This decision, in principle, coincided with the prognoses and the options proposed by Danilov Yu. G. and Yegorov Ye. G., the researchers of the R&D Institute for Regional Economy of the North at the Ammosov North-Eastern Federal University, to the leaders of the Republic of Sakha (Yakutia) in November 2010 regarding the diamond company going public.
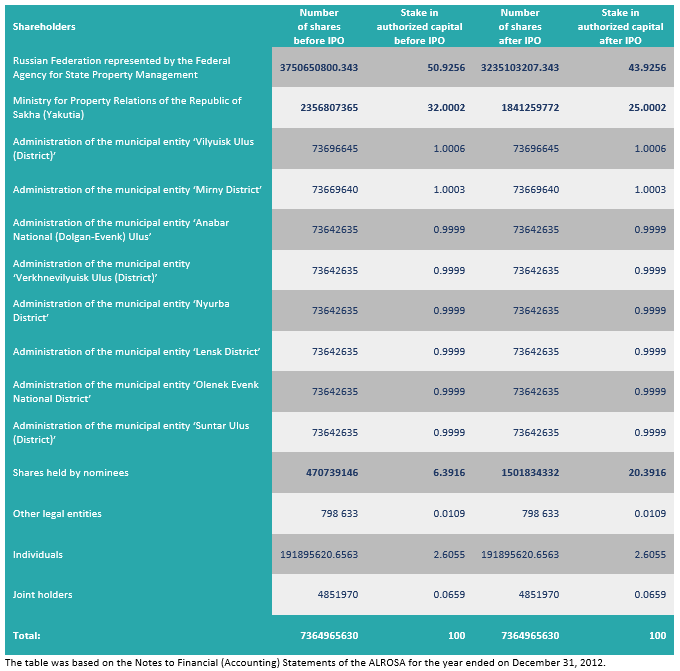
A further rise in the share prices during the subscription contributed to floating the ALROSA’s shares at their price, considered optimal by most analysts. The company’s market capitalization reached over USD8 billion. The privatization carried out by ALROSA resulted in the redistribution of the company’s shares among its key shareholders. To say that the ALROSA’s shares did not go to a big market player would be premature even now, because over 20% of the shares are held at present by nominees, and the fact that the company’s share price continued to grow after the placement is just another proof of the ongoing consolidation of this package (Table 2).
Table 2
Major shareholders of ALROSA before and after the IPO
Round 2, SPO of the ALROSA’s shares
On November 18, 2013, the Rosimushchestvo (Federal Agency for State Property Management) and the Minimushchestvo (Ministry of Property Relations) of Yakutia signed a shareholders' agreement regarding ALROSA (they own 43.9% and 25%+1 share, accordingly) stating that within the next five years, the government’s stake in the diamond company should not be less than the controlling one. The agreement is subject to an automatic renewal for another five years unless otherwise agreed by the Parties.
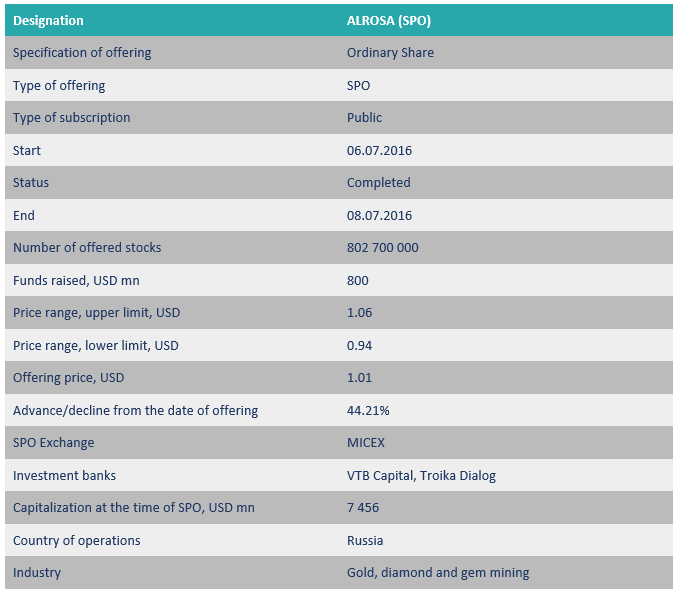
Nevertheless, in July 2016, the secondary public offering (SPO) for the ALROSA’s shares was carried out within the framework of the privatization programme. The company was evaluated at ₽478.7 billion. This sale of shares was actually the first large-scale deal after a long break in the mass privatization and was carried out in the environment of sanctions. During the sale of the ALROSA’s shares, the discount to the market price was 3.77%. The government of the RF sold 10.9% of the ALROSA’s shares, or 802.7 mn shares, for ₽52.2 billion.
The bid book for selling a 10.9% shareholding was oversubscribed almost by three times. The total demand in the bid book for company’s shares was two times more than the offer. The bids under ₽65 per one ALROSA’s share were not satisfied as the demand level was about ₽66 per one share.
About 30% investors subscribed for shares were the citizens of Russia, another about 30% were investors from Europe, about 25% - from the Middle East and Asia. The remaining shares were for the investors from other countries and continents, including the USA. The placement of shares was carried out amid the recovery of the Russian stock market. Specifically, the MICEX Index grew by 19% from the beginning of the year and was at the level of 2008. Table 3 shows the results of the placement of shares.
Table 3
The data on the placement of the ALROSA’s shares during SPO
Round 3, final
At present, the ALROSA’s shareholders include the Russian Federation in the name of Rosimushchestvo - 33.02%, the Republic of Sakha (Yakutia) - 25%, uluses (districts) of Yakutia - 8%. About 34% of shares are free-floating. And in 2019, due to the increasing Russia’s and Yakutia’s deficits, most probably, 8% of shares will be sold. In this case, the Republic will encounter a dilemma – what parcel of shares to sell. In my opinion, it is necessary to sell the municipal shares of ALROSA, and the money raised should be invested in solving the urgent problems facing these districts, in particular, in providing the population with pure water, construction of roads and for other needs.
Yury Danilov, Ph. D., Director of “Expert” Information and Analysis Center at Ammosov North-Eastern Federal University
