The dynamics of the diamond production in 2014-2018.
In July this year, the Kimberley Process will release the statistics on the rough diamonds mined and sold by the countries in 2018. Last year, the same 23 countries were in the commercial diamond mining as in the previous years. Without this data at hand, we can estimate rather accurately the actual diamond production as well as the financial results of the global rough diamond trade based on the sum of the major diamond miners’ performance data in 2018.
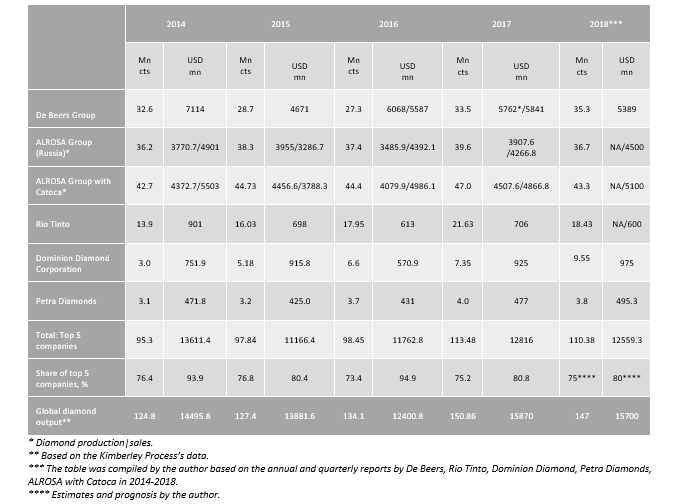
The dynamics of changes of this performance data is given below (Table 1).
Table 1
The world’s major diamond mining companies in 2014-2018
Brief summary
Simple calculations based on the averaged share of top five diamond mining companies that equals approximately three-quarters of the actual global diamond production in carats and four-fifths of the rough diamond sales value in dollars show the predicted results. So, in 2018, the global diamond production will be 147 mn carats and the rough diamond sales value will make US$15.7 bn. As compared with 2017, in 2018 there was some decline in the rough diamond output: by 2.5% by volume and by 1% by value. This suggests that the world diamond mining industry has reached its peak level.
Given that the global rough diamond market today is sustainable and demand for rough diamonds is high, it’s hardly possible that any dramatic change in the situation will occur in the diamond mining countries and world diamond trading centres in 2019, so Russia and the ALROSA company will still maintain their lead in diamond production.
Yury Danilov, Ph. D., Lead Research Fellow at the Subsoil Use Innovative Economics Laboratory of the North-Eastern Federal University
