2018 World Diamond Pipeline
This year, a well-known global diamond business analyst, Chaim Even-Zohar, published the structure of the global diamond pipeline in 2018 (Diamond Pipeline 2018. IDEX Magazine No. 4, April 2018). This time, such enterprises as ALROSA, De Beers and others appeared in it. The fast-growing market for synthetic rough and polished diamonds is shown, which already accounts for 5% of the natural market. The forecast for 2018 on the natural diamonds sales was $15 bn, and the value for cutting diamonds in Russia was $300 mn.
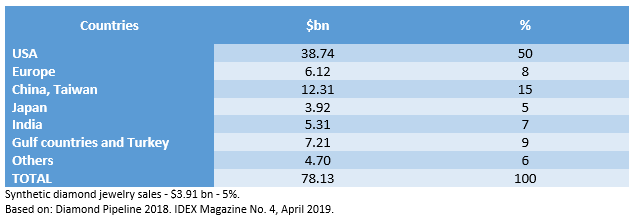
Based on this data, tables have been made up that characterize the global diamond market (Tables 1, 2, 3, 4).
Table 1
World diamond mining by countries
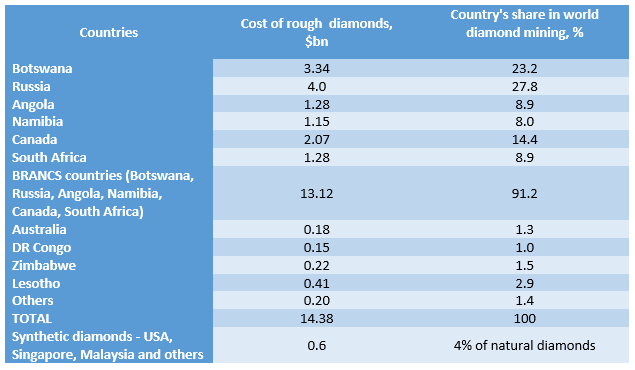
Table 2
World diamond mining by enterprises
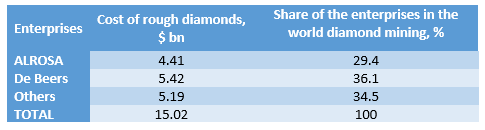
Table 3
Diamond value added after cutting, by countries
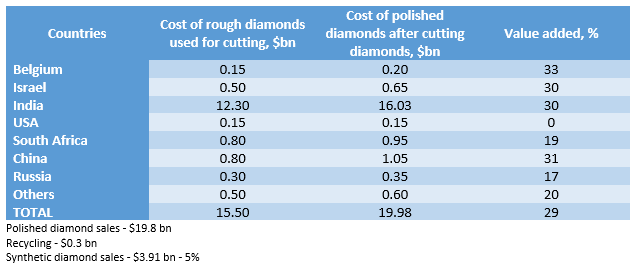
Table 4
Diamond Jewelry Sales by countries
Prospects for the diamond market until 2020
Using the method of a triangular diagram developed by the author, let us look at the prospects for the development of the global diamond pipeline in 2019-2020. Figure 1 shows the world diamond pipeline pattern in 2006-2018 made using the triangular diagram.
Fig. 1. The world diamond pipeline in 2006-2018.
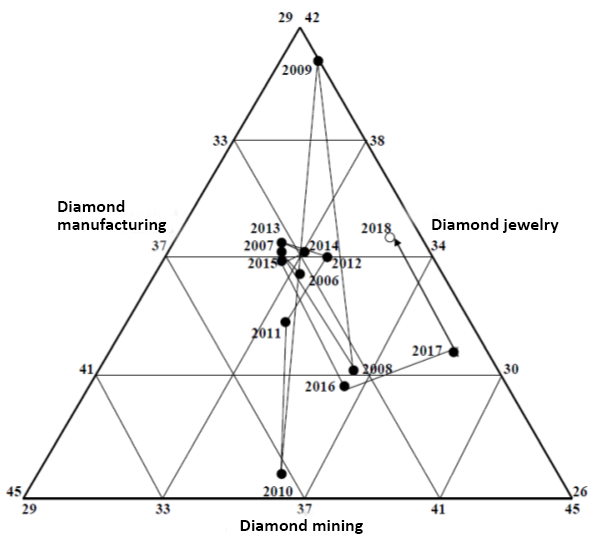
The 2018 point is not far from that of the 2009 crisis year, which may indicate the forthcoming severe recession in the global diamond market. It will primarily make impact on diamond cutting and mining.
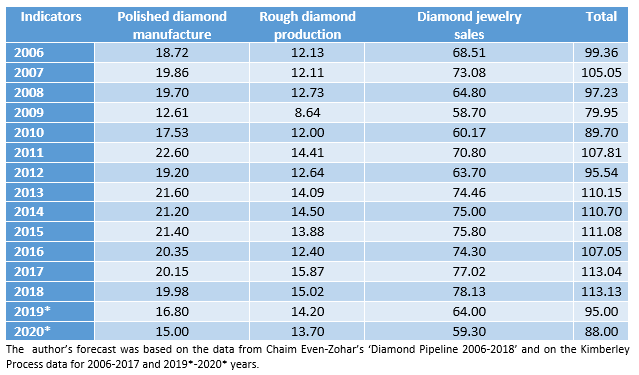
Table 5 shows the performance of the global diamond market in 2006-2018 and the author's forecast for 2019-2020.
Table 5
The global diamond market in 2006-2020, $bn
Brief conclusions
1. As the global diamond market is not sustainable today and the demand for diamonds is declining in 2019, it is unlikely that a drastic change will occur or the situation will change for the better given the tensions in international trade and politics.
2. The study of the world diamond pipeline using a triangular diagram shows that in 2018, it is close to the 2009 global diamond business crisis, and in future, in 2019-2020, there will be further exacerbation of the recession due to the problems in the midstream of the diamond pipeline.
3. If we consider the prospect for diamond-mining countries and enterprises, Russia and Russian ALROSA company will continue to maintain their leading positions in the world in terms of production and value of rough diamonds sold.
Yury Danilov, Ph. D. in Economics, independent analyst and expert
