Recently there is much talk going on about possible transformation of ALROSA into a publicly traded corporation and a virtual IPO on the part of this company and its subsidiaries. This brings forth the problem of a tentative evaluation of these companies and their shares placed on the market.
In actual practice the following methods are used to evaluate corporate stocks:
- by the company’s return on investment for a certain period taking into account inflation and alternative investment options;
- by the amount of corporate assets per one share;
- by coefficients and indices comprehensively describing the business under evaluation.
In Russia corporate stocks may be evaluated by way of a survey of probable buyers/investors who may be divided into the following types:
Type I – investors buying shares in the hope to get dividends;
Type II – investors buying shares for the purpose of control over the business and aiming not only at dividends, but also at active participation in developing the company’s strategy;
Type III – investors buying shares for a short term for the purpose of subsequently reselling them at a higher price.
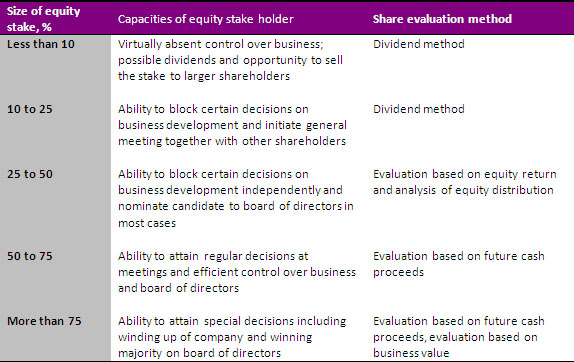
Depending on the purpose of stock purchase a specific method may be chosen based on the size of the equity stake bought (Tab. 1).
Table 1
For reference:
Shareholders of ZAO AK ALROSA
- The Russian Federation represented by the Federal Agency for State Property Management – 50.9256% of shares;
- The Republic of Sakha (Yakutia) represented by the Ministry for Property Relations of the Republic of Sakha (Yakutia) – 32.0002%;
- Eight uluses (districts) of the Republic of Sakha (Yakutia) – 8.0003%;
- Others legal entities and physical persons – 9.0739%.
In case of public companies their share value is established by stock exchange trade, i.e. by the market. Since shares of the Russian diamond-mining companies are not traded at any stock exchange, they may be evaluated by a comparative method, correlating their technical and economic indicators with similar enterprises and using coefficients.
Table 2
Major mining companies of the world in 2008 - Forbes
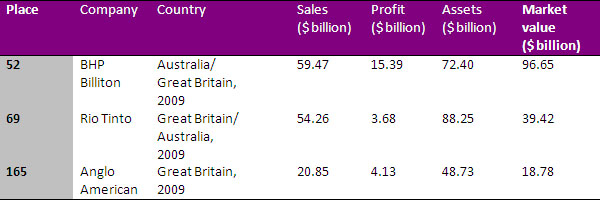
Global 2000. Special Report 04.08.2009.
On the basis of the above data, having made and solved the equation in three unknowns, the author of this article has received the following empirical formula for value calculation (C):
C = 1.19 ∙ Csls + 3.76 ∙ P – 0.44 ∙ A,
where: C is the market value of the company, $ billion;
Csls is the sales (proceeds), $ billion;
P is the company profit, $ billion;
A is the value of company assets, $ billion.
The annual reports of the diamond-mining companies in the Republic of Sakha (Yakutia) for 2008 were taken to calculate their possible market value in accordance with the above formula (Table 3).
Table 3
Major financial and economic indicators of the diamond-mining companies of Yakutia in 2008 and their calculated market value
Roubles million / USD million
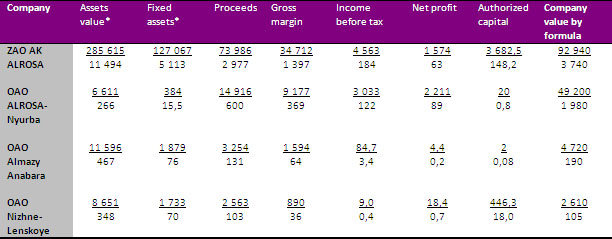
* As of 31.12.2008
According to the Central Bank of Russia, in 2008 1$ = 24.85 roubles
The obtained calculated data are quite unbiased in describing a possible stock value of the diamond-mining companies in Yakutia. It is possible to draw the following conclusions on their basis:
1. The market value of ZAO AK ALROSA’s stock runs considerably below its assets and fixed assets value which is due to the company’s present difficult financial situation. Therefore, making company public, which is a long overdue necessity, should be carried out without an IPO.
2. The shares of OAO ALROSA-Nyurba 87.57% of which are owned by ZAO AK ALROSA appear to be the most perspective and favorable for a public placement.
3. In the current post-crisis situation in the diamond-mining industry OAO Almazy Anabara and OAO Nizhne-Lenskoye also look premature to go public.
Yuri Danilov, Senior Research Fellow, Department of Rough and Polished Diamonds Complex Economy, Institute for Regional Economics of the North (Federal State Scientific Entity)
