ALROSA’s capitalization
The company’s charter capital currently stands at 3,682,482,815 rubles divided into 272,726 shares with a nominal value of 13,502.5 rubles. Prior to the federalization of ALROSA it was 2,700,500,000 rubles divided into 200,000 shares with a nominal value of 13,502.5 rubles. It is supposed to issue additionally 76,362 shares which will make, according to earlier estimates, 28% of the currently available capital, or 21.87% of the charter capital after the placement. Each share will be converted into smaller shares denominated at 0.5 rubles, i.e. every minority shareholder will own 27 005 shares instead of one share.
The proportion of the shareholders’ stakes in ALROSA will change as follows:
- The Russian Federation represented by the Federal Agency for State Property Management - 39.79%;
- The Republic of Sakha (Yakutia) represented by the Ministry of Property Relations of the Republic of Sakha (Yakutia) - 25.0% + 1 share;
- Eight uluses (districts) of the Republic of Sakha (Yakutia) - 6.25%;
- Other legal entities and individuals - 7.09%;
- The additional issue of shares - 21.87%.
Thus, a potential investor having bought the whole package and additionally acquiring just over 4% of shares on the open market may turn into a blocking minority (25.0% + 1 share) like the Republic of Sakha (Yakutia). This may explain the rush currently observed in Yakutia’s "gray" market, where prices have soared above RUB 800,000 per share.
To determine the market value of ALROSA’s shares and the volume of investments to be attracted at a subsequent placement of additional shares it is needed to estimate the value of the company. According to the calculations made by the author, who used different methods of assessment in 2010-2011, the company's value ranged from $3.74 to $5.35 billion. Given that the stock market and respectively the pace-setting global and Russian stock indices have recently increased gradually approaching the pre-crisis highs, it is necessary to specify the evaluation to determine the amount of funds to be raised in case of an IPO (Table 1).
Table 1
Estimating the value of ALROSA
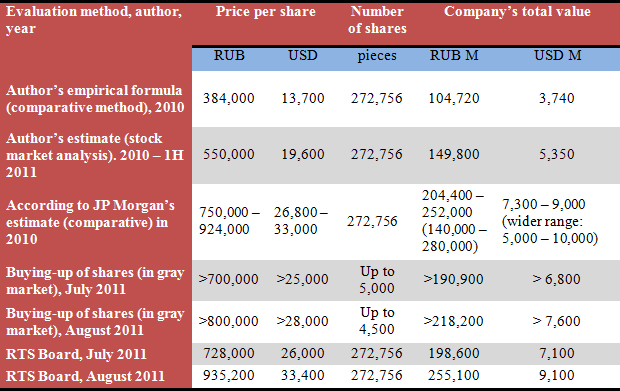
U.S. dollar exchange rate is taken as $1 = RUB 28.
Free float of shares
Starting from July 18 this year, ordinary shares of ALROSA were included in the RTS Board trading system. It is used for indicative quotation of securities not admitted to trading on the RTS. Securities included in the list of instruments circulated by RTS Board (such as shares and bonds) are not publicly traded on stock exchange sessions and their quotes cannot be the basis for calculating the market value and market capitalization. They are just the first step to float an issuer's securities on the stock market. The second stage is to admit the issuer's securities to trading on the RTS. ALROSA’s full listing is scheduled for 2012 after its shares will be split and their face value will be reduced 27,000 times to 50 kopecks.
Possible bidders within RTS Board may be investors who bought the company’s equities before its transformation into an open joint-stock corporation from a closed joint-stock entity. Among them, experts point to the Vostok Nafta Investment Foundation (owning 0.46% of the company’s capital) and the KIT Finance Bank (0.83%). Because they are interested in increasing the value of the acquired shares, it is possible that the hike in the stock price from $26,000 to $33,400 (28.5%) in August on RTS Board may be simply explained by buying and selling ALROSA’s shares between these investment companies.
Capitalization of diamond mining companies
Thus, the quotation of ALROSA shares in the "gray" market is more equitable, which is confirmed by the empirical formula of the company’s value resulting from a graphical analysis of the public diamond miners’ stock value (Table 2, Figure 1).
Table 2
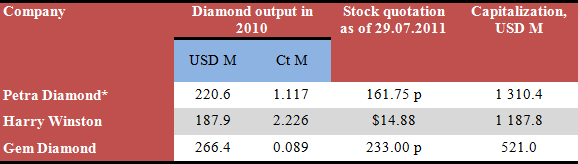
* Fiscal year ends on 30/06 next year.
U.S. dollar exchange rate is taken as £1 = 100 p (pence) = $1.6207; $1 = RUB 28.
In August 2011, Russia’s Federal Financial Markets Service (FFMS) registered the offering memorandum for 7,364,965,630 ordinary shares of ALROSA placed by way of splitting and converting the previously released shares into new shares with a par value running at RUB 0.5. Thus, in a possible IPO it will be necessary to register the issue of more than 2 billion shares of new denomination.
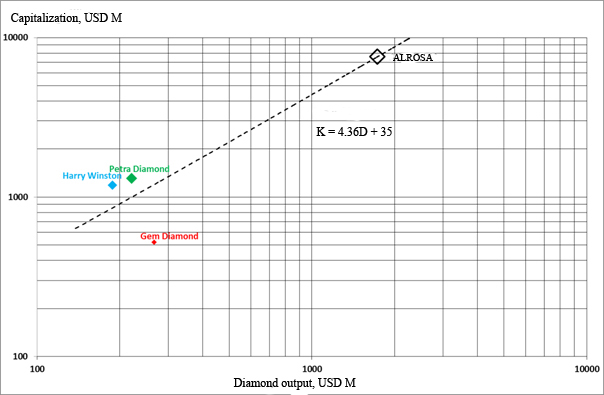
Fig. 1. Dependence of diamond mining companies’ capitalization on their diamond output.
Possible value of Yakutia’s diamond mining companies calculated by the author’s empirical formula is given in Tab. 3:
K = 4.36 D + 35,
Where: K is market capitalization in USD M;
D is diamond output in USD M.
Table 3
Capitalization of diamond mining companies in the Republic of Sakha (Yakutia)
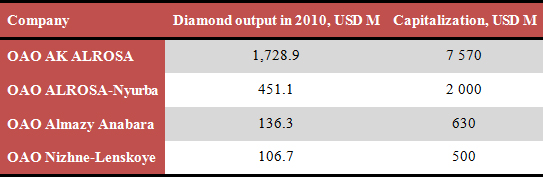
Thus, if ALROSA will undertake an IPO today it may still raise about $1.5 billion. On the other hand, it is possible to attract a larger amount adding the shares of the company’s subsidiaries to the offering. However, the overall decline in all global stock markets, which began last August, heralds a new phase of the global crisis and in the future these figures may be reduced.
Crisis in August
Since early August, global stock markets turned feverish. There was a sharp decrease in the indices of all the leading stock exchanges, which is a wake-up call for the global economy, since, as it was shown by the recent crisis, a downturn in the stock market is followed by a drop in the commodities market, which is accompanied by drastic changes in the rates of world currencies. Also noteworthy is the fact that during such periods of crisis gold, which seems to be related to commodities, but plays an important role as a currency, goes up in price. Totally the opposite happens to prices for rough and polished diamonds and jewelry considered to be luxury goods. In addition, it should be said there is a time lag after the fall of stock prices. It lasts three months for raw materials and currencies and up to one year for luxury goods. This means that a drop in demand for rough and polished diamonds will not happen before the next summer.
Yuri Danilov, Ph. D., Senior Research Fellow, Institute for Regional Economics of the North
