World diamond production is able to grow to 209 million carats in 2020 driven by newly commissioned projects, according to Bain & Company experts. However, diamond miners have limited capacities to increase output, and they will not be able to keep apace with rising consumption in emerging markets. These factors are most likely to bring about rough scarcity in the market in the next decade.
Production: Hope pinned on "new" projects and "new" countries
The baseline scenario for the industry’s development as it is seen by Bain is drawn on current rates of production displayed by diamond mining companies and on the development prospect they have today.
Global diamond output in 2010 reached 133 million carats and according to Bain its increase in 2011 will be insignificant. The diamond industry is still far from its pre-crisis level of 150-160 million carats – it was too much affected by the decline in production during the economic downturn. In 2008-2009, diamond output was reduced by all diamond mining companies, except Russia’s ALROSA (which could not bring it to a halt due to its social obligations and continued to work "for stock").
Bain’s experts suggest that pre-crisis production figures will be matched by 2017 - due to the recovery of reduced output, also assisted by newly launched projects that are currently being implementing by industry leaders.
The new projects (13 altogether) will give a total of 23 million carats of rough to the market. The most important of these projects are:
- Gahcho Kue in Northern Canada, owned by De Beers, targeted to produce 6 million carats by 2020;
- Karpinski Diamond Pipe in the Arkhangelsk Region (Severalmaz, a subsidiary of ALROSA), which will give up to 5 million carats a year, if developed;
- Bunder in India (Rio Tinto) with a forecast output of 3 to 5 million carats a year.
The remaining projects are operated by 'second tier' companies, including those for which this is the first experience in diamond mining. These include, for instance, the Grib Diamond Pipe initially planned to sell by LUKOIL, a Russian oil company, but now intended to develop on its own. Three of the 13 new projects will start mining operations already in 2011 - including AK6 (Lucara), Kao (Namakwa Diamonds) and Liqhobong (Firestone). According to Bain, mining at the Grib Diamond Pipe may be expected to start at the end of 2012.
If implemented, the baseline scenario will allow the global diamond mining to reach the level of 160 million carats in 2014 and 170 million carats in 2016. In subsequent years, production is expected to grow just slightly, and by 2020 it will go up to 175 million carats. The reason is the inevitable depletion of those reserves that are now being worked out, and the absence of other major new projects (comparable in importance with the above). More than that, experts have concluded that even if a new diamond deposit having significant reserves will be found in the coming years, exploration and preparatory work will take a long time, and until 2020, this new project will still not be able to change the overall picture.
There is a more positive scenario, based not only on potential production of the current industry leaders, but also taking into account the emergence of new diamond areas. According to Bain, Zimbabwe and the DRC could become such areas, since they have capability to produce significant amounts of rough diamonds. In that case, if the political situation in both countries will be stabilized, the DRC and Zimbabwe may contribute to the diamond market, driving global output to 209 million carats in 2020.
There is also a conservative scenario considered by Bain’s experts in case a difficult economic situation and technical reasons will prevent major diamond miners to make their operations running at full capacity. In this case, global diamond output will remain at the current levels until about 2014, after which (due to gradual completion of the current projects) it will smoothly decrease and reach 127 million carats in 2020.
Consumption: Staking on India and China
In their forecast for diamond demand, experts rely on two key indicators: consumer spending in mature economies and ongoing urbanization in emergent nations resulting in a greater number of "middle class" population, especially in China and India.
The financial crisis in 2008 affected diamond demand as much as diamond output: before the downturn, demand exceeded $15 billion, but in recession it fell to about $10 billion. However, consumption is recovering faster than supply. According to experts, even under the baseline scenario of development for the diamond industry consumption will return to pre-crisis levels in 2013 reaching the level of 196 million carats and in 2020 it will grow to 247 million carats.
Even considering the baseline scenario Bain’s experts are positive with regard to consumer spending in mature economies (U.S., Europe, Japan and the Gulf countries). They assume that consumer spending in these countries will grow over the next 10 years and totally will reach $24 to $29 trillion. So far, the Persian Gulf accounts for the lowest share in spending (merely $0.5 billion in 2010), but it is this region which will demonstrate the most rapid growth - 5% by 2020.
Simultaneously, they expect a significant increase in the number of middle class (those earning above $15,000 per year) in China and India – approximately to 469 million households in 2020 from 193 million households in 2010.
According to expert evaluations, these positive factors will increase demand for rough diamonds up to $18 billion as early as 2014 and to $23 billion in 2020. In this case consumer markets will continue to be redistributed: if before the crisis about 44% of consumption was generated by the U.S., now this percentage is lowering and will drop to 35% by 2020, while the share of emerging markets in China and India will increase to 30%, whereas before the crisis it did not exceed 20%.
In parallel, Bain is also describing an optimistic and conservative scenario. The conservative option suggests another global recession, with the world’s GDP growing by less than 2.5% - this will lead to slower growth in emerging nations and stagnation in mature economies. However, even the conservative version allows for increased diamond demand – only at a more modest scale, from 133 to 211 million carats.
The optimistic scenario suggests an even greater increase in consumer spending and higher global GDP growth rate, above 3.9% per year. Within this scenario, demand for diamonds will soar to 371 million carats.
Market balance: Shortage in any case
As it is estimated by Bain, regardless of the scenarios the diamond market will be exposed to shortage of rough in the next 10 years, the difference being only in scale.
In 2010, the diamond market emerging from the crisis dip recovered its balance: supply and demand were at a level about 133 million carats. But starting from 2012, experts expect a change.
Market balance in 2012 (million carats):
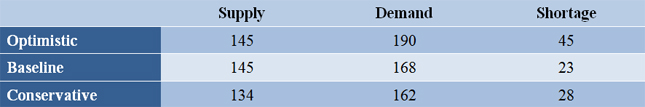 Thus, experts believe that already in 2012 the diamond market will no longer be balanced and will face a shortage of at least 20 million carats - that is, about 16-20% of output. And this trend will be maintained in the future: the gap between supply and demand will only continue to grow.
Market balance as projected by Bain in 2020 (million carats):
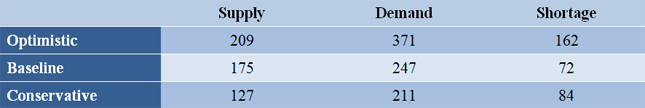 This being said, there is reason to believe that development of supply and demand under different scenarios is unlikely. Diamond miners will not be focused on increased output, if consumption will stay flat - it may lead to lower prices for rough.
Thus, by 2020 shortage in the rough market may reach at least 72 million carats - these volumes are comparable not with 15-20% of global output, but with a half of it.
Elena Levina for Rough&Polished
