ALROSA held its first Investor Day in London on April 7, 2015 introducing its plans for the current year and sharing its vision of the market situation. The Acting President of ALROSA, Ilya Ryaschin confirmed that diamond mining remains a strategic priority of the company, as well as getting rid of non-core assets and deleveraging. The market did not expect any course-changing from the management of ALROSA, although from the end of April the policy of the world’s largest diamond miner will be determined by its new president (most likely, this position will be taken by Andrey Zharkov, deputy head of Gokhran). In any case, the head of ALROSA will take some time to get on the inside, so any sharp corrections in 2015 are unlikely. It won’t be superfluous to put all the essentials contained in the speech of Ilya Ryaschin and in the presentation of ALROSA together to picture the current state of affairs.
MARKET AND PRICES
The start of the year 2015 was not easy for the diamond market. India, the largest producer of polished diamonds slashed its diamond imports by 30%, which could not but have an impact on diamond prices, which fell by 3% in the first quarter of 2015. ALROSA allowed its customers to defer up to 30% of purchases in January and 10% in February and March. The company expects renewed demand in the second half, when diamond cutters and jewelers will finally start to replenish their stocks, due to which prices are to rise by 6% to the current level. Based on this, ALROSA retains its outlook for a 3-percent rise in rough prices by the end of the year. However, there are also more pessimistic assessments coming, for example, from Deutsche Bank, which expects the level of prices to remain flat towards the end of 2015 as compared with the beginning of the year.
According to ALROSA’s estimate based on the forecasts outlined by Bain, supply and demand in the diamond market will be balanced until 2018, after which diamond shortage will prevail. Diamond output in 2019-2024 will go down by an average of 2% per year due to the depletion of diamond mines in Australia and Canada. This will contribute to higher prices.
PRODUCTION AND SALES
It is in 2019, when ALROSA will bring its output to its peak - 41.5 million carats. Its production forecast for 2015 is 38.2 million carats of rough diamonds, which will permit it to keep the lead.
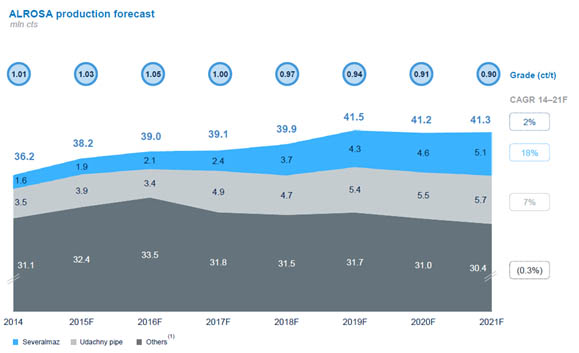
Reaching the targets set by Severalmaz (1.9 million carats) and by the Udachny underground mine (0.8 million carats) appears to be the main driver for production growth in 2015.
ALROSA also confirmed its outlook for sales in 2015 - 40 million carats, including 2 million carats from the company’s stockpile. A similar level of sales from the stockpile is planned for 2016 (with a total sales outlook of 41 million carats).
ALROSA stockpiled 14.7-14.8 million carats of diamonds at the end of 2014, of which 9 million carats of gem quality diamonds and 6 million carats of industrial diamonds.
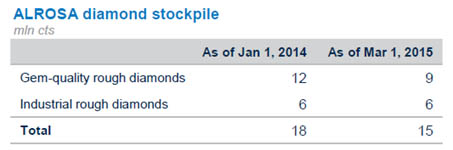
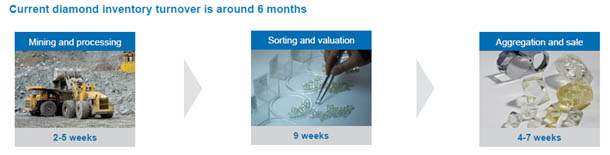
In the first quarter of 2015, ALROSA did not sell diamonds from its stockpile, but the miner will reduce its stock by accelerating the sale of rough it contains (currently being sorted and evaluated). Right now it takes 6 months to make a turn-over diamonds in the stock, and the company plans to reduce it to 4 months by automating one of the "long-running parts" - the sorting process.
The sales pattern will most likely remain unchanged (gem quality diamonds - 70%, industrial diamonds - 30%). At the same time, according to the presentation of ALROSA, gem-quality diamonds accounted for 97% of the revenue gained in 2014. Large diamonds (exceeding 10.8 carats) comprising less than 1% of the miner’s sales in terms of weight drew 11% of the total earnings.
ALROSA does not expect significant shifts in the average price per carat in 2015 due to changed diamond mix. More likely than not, the company will not sell diamonds to Gokhran, Russia’s state repository, this year.
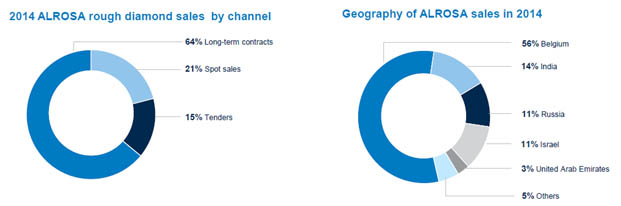
Long-term customers buy 64% of rough sold by ALROSA. Belgium’s share was 56% in 2014, while India accounted for 14% and Russia’s domestic market for 11%.
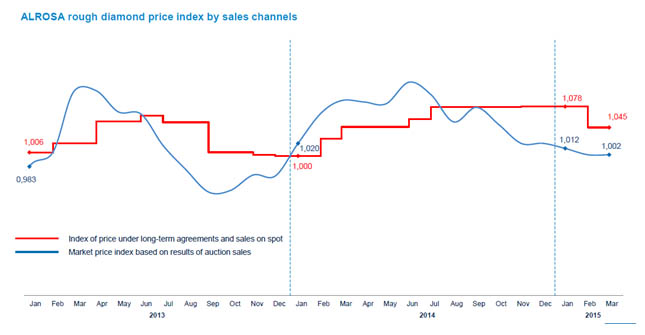
ALROSA’s being geared to long-term contracts is justified - the price index within the frames of its long-term contracts starting from August 2014 was above the price level registered at auctions.
Responding to a question about the threat to diamond miners from synthetic diamonds, Ilya Ryaschin said that synthetics were such only if disguised as natural stones. Special devices were developed to detect synthetics and mandatory certification was introduced for diamonds over 1 carat. Synthetic diamonds cannot get a certificate. Major diamond producers including ALROSA, De Beers and Rio Tinto agreed to establish an association at a meeting in London last March.
COSTS
ALROSA intends to decrease capital investments progressively by completing its key projects and due to the ruble devaluation - from 35.6 billion rubles in 2015 to 21.8 billion rubles in 2018.
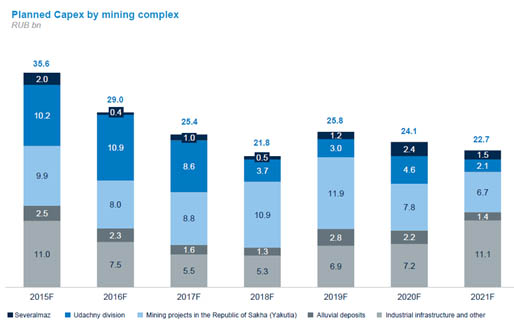
Currently, the share of dollar-denominated costs in ALROSA’s capex does not exceed 10%, but the company wants to reduce it further through a program of import substitution.
ALROSA expects its costs will grow by 12-13% in 2015, which roughly corresponds to the official inflation forecast given by the Ministry of Economic Development.
OUTLOOK FOR PROFITS AND DIVIDENDS
Despite a net loss at the end of 2014, the management of ALROSA will recommend to pay dividends at the level of 2013, i.e. in the amount of 10.83 billion rubles (1.47 rubles per share), which is equivalent to $ 200 million at the rate of 55 rubles to the US dollar (thus making a 2% dividend yield). The final decision is still pending, and the company continues to discuss the level of dividends with its major shareholders in the run-up to the Supervisory Board on the 23d of April 2015, which will address this issue.
ALROSA expects a net profit of RUB 100 billion in 2015 (at the rate of 56-58 rubles to the US dollar). With this net profit and proceeding from the current dividend policy, dividends may reach 4.9 rubles per share yielding up to 7%, according to UBS.
In line with the dividend policy of ALROSA, dividend payments are to be at least 35% of its net profit under the IFRS. The company does not intend to change this policy tying payments to the level of debt or cash flow. Payments may also increase within the frames of the current pattern. "The dividend policy of the company says that we have to pay at least 35%, but we can pay more. For this, it will be enough to give recommendations," Ilya Ryaschin said.
DEBT
Besides the redemption of ruble bonds worth $ 334 million scheduled for this year, ALROSA wants to prepay $ 1 billion of debt from its operating cash flow, reducing the company’s total debt to $ 2.3 billion. The target set for the net debt / EBITDA ratio is 1x (vs. the current 1.9x). The debt repayment schedule is acceptable for the company and ALROSA is to pay about $ 435 million of bank loans in 2016.
STRATEGY
The company confirmed its intention to focus on diamond mining. This segment remains to be the most profitable in the entire "diamond pipeline" (its operating margin being 21-25% compared to 3-4% in diamond manufacturing and 4-18% in retail jewelry sales). The miner has no plans to increase its presence in the low-profit diamond manufacturing business or develop new gold and platinum deposits (except the accompanying precious metals to be extracted on the placers developed by Almazy Anabara).
The company continues its program aimed at divesting most of its non-core assets. Their number will be reduced from 39 last year to 20 in 2020.
The largest possible deal – to sell gas assets to Rosneft – may fail to be completed by the end of 2015, although there is a chance it will be closed. The associated news coming out so far are positive - Rosneft proposes to drill new exploration wells following the successful drilling of one well and good data on reserves. ALROSA expects to transfer all of its social assets and 6 airports to Yakutia this year.
DEVELOPMENT PROJECTS
Though the acquisition of the Grib Mine from LUKOIL is still possible, this option looks more theoretical. The company is currently looking for mergers and acquisitions outside of Russia, among other things mulling over several new projects in Angola showing promise. These plans are of a long-term character and at the moment ALROSA is rather evaluating potential projects than making real steps to take them up. Even if it is decided to allocate substantial investments, it will not happen in the next two years. ALROSA does not plan to raise its stake in the Angolan Catoca mine.
ANALYTIC EVALUATIONS
Commenting on the results of the Investor Day held by ALROSA, analysts from investment banks mainly paid attention to the fact that the company had confirmed all of its major projections. As a consequence, they confirmed their positive recommendations for its shares.
The assessment given by the management of ALROSA coincides with the forecasts from Deutsche Bank, or even outstrips them, according to a survey by DB. This investment bank has confirmed its “Buy” rating for the stock issued by ALROSA despite the currency risks and diamond market conjuncture. The price target for ALROSA shares set by Deutsche Bank is 108.5 rubles (at 12:00 on April 10 ALROSA’s stock was worth 63.4 rubles per share).
It is unclear how the strategy and plans of ALROSA may change when a new president of the company will be appointed, says Morgan Stanley.
Taking into account the miner’s lower production costs, Citi raised the projected price of ALROSA shares by 6% to 76 rubles.
According to the estimates of UBS based on the EV / EBITDA multiple, ALROSA shares are currently undervalued and their annual price target is 95 rubles.
ALROSA shares are attractive, especially for long-term investors, says BCS, since there are presently no short-term drivers.
Sberbank CIB joins this evaluation. "ALROSA’s securities are rather a bet on the upside than on dividends," the report released by this investment bank says. This position is based on the fact that ALROSA, while improving its cash flow and financial position, may potentially consider acquisition opportunities in Russia and Africa, preferring assets at the exploration stage. "Since we do not observe any short-term upside for the luxury market, we believe that quotes for ALROSA shares will be determined by the movement of the foreign exchange market", said Sberbank CIB.
Sergey Bondarenko for Rough&Polished
