After many years of growth there was a slump in diamond output and diamond prices which may continue until the situation on the world financial market is completely restored. In this context there may be two ways of development in the world diamond business. According to a positive scenario, diamond output and parity between demand and supply will be restored by 2010. A negative scenario suggests a deeper type of recession and slow recovery of the diamond market by 2013-2015.
A diamond output forecast up to 2020 based on the current situation in the diamond business and its positive and negative alternatives of development is given in Table 1.
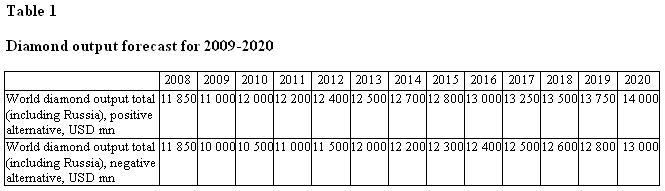
Despite the ongoing world economic crisis it is expected that by 2020 the diamond market will experience scarcity of natural diamonds especially in the category of large-size stones of high quality, so by this time the mineral resources base for diamond mining should be significantly expanded and this involves stepped-up geological exploration. Besides, almost all of the world’s largest diamond fields are expected to switch over to underground mining.
Based on the outlook of diamond jewelry demand in the world both for positive and negative alternatives there has been made a calculation of eventual balance between the world’s rough diamond demand and supply for the period up to 2020 presented in Table 2.
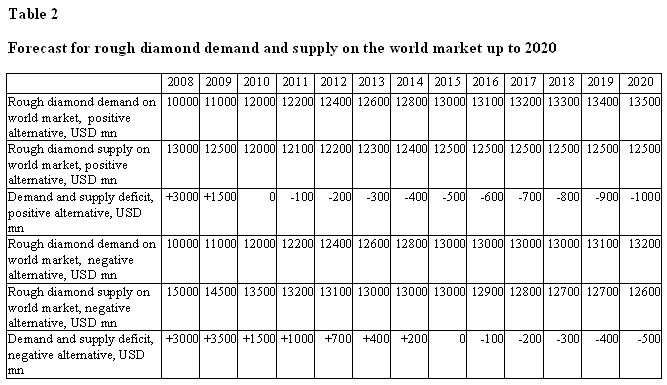
The scarcity of rough diamonds used for manufacturing diamond jewelry, which will reach $0.5-1.0 billion by 2020, will stimulate higher prices for rough diamonds and contribute to diamond mining expansion.
In 2009-2010, if Russia will maintain the 2008 level of diamond output it will give it a chance to have a significantly larger share in the world supply of rough diamonds, which is currently the main problem for the Russian diamond industry. During these years, the ALROSA Group due to the worldwide crisis in the diamond business will have a unique chance to become the world’s leading diamond-mining company.
Table 3 gives figures related to diamond output in 2006-2009 by the largest suppliers of rough diamonds to the world market.
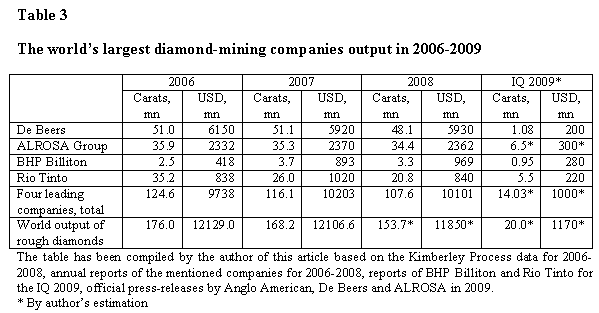
In the first quarter of 2009, the four leading rough diamond miners, which are likely to preserve their positions unchanged in the nearest ten years, jointly produced about 85% of the total worth of the world’s rough diamonds and 70% of the world’s physical output. These producers include: ALROSA (32.5% of physical output and 25.6% of the total worth of sold rough in the IQ 2009); De Beers, including its diamond-mining enterprises in South Africa, Botswana and Namibia (5.4% of physical output and 17.1% of the total worth of rough in the IQ 2009); BHP Billiton and Rio Tinto (4.7% and 27.5% of physical output and 23,9% and 18,8% of the total worth of rough in the IQ 2009). It should be noted that due to the timely measures taken by the Russian government and ALROSA’s management the company came to the fore in rough diamond output. Yet it has to solve the problem of selling rough diamonds on the international market which is a first-rate target in a low market environment.
Yuri Danilov, Senior Research Fellow, Department of Rough and Polished Diamonds Complex Economy, Institute for Regional Economics of the North (Federal State Scientific Entity)
