In case ALROSA will offer a public subscription at prices lower than those estimated, this company is a good investment, says Maxim Lobada in an article posted on the Investcafe portal. In his opinion, it is most likely that before an IPO the company will split its stock to increase liquidity, which should attract individual investors.
In summer 2010, my colleague, Mikhail Fyodorov, made a rough assessment of ALROSA, comparing it with Russian companies, Norilsk Nickel and Polyus Gold, and the result was $35,000, the author writes. I decided to make my own comparative analysis to assess the company before and after the would-be IPO.
To evaluate ALROSA I used a comparative approach. The EV/S multiplier reflects the value of a company taking into account its debt burden and thus reflecting its truest value. The company was assessed based on its performance figures in 2009 and on its forecast data for the end of 2010. The multipliers were assigned similar weights.
Diamond corporations quoted at LSE and NYSE and having market capitalization exceeding $100 million were chosen to play the role of peers companies.
Peers’ multipliers
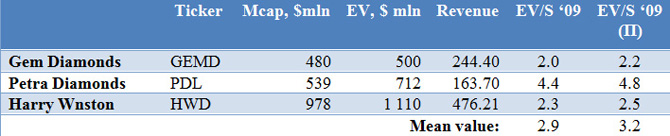
Source: Data released by companies, NYSE and LSE; Investkafe estimate.
Evaluation of ALROSA
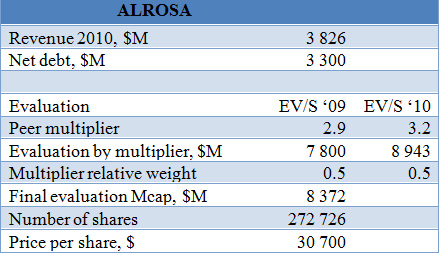
Source: AK ALROSA, Investkafe forecasts
The issuer’s prognostic value based on peer multipliers runs at $ 8.4 billion, or $30,700 per share.
If ALROSA ventures an IPO, about which I have little doubt, it would be fair to add a 10-percent premium for the company’s scale of business (state monopoly) to the value estimate. Given the rise in prices for rough diamonds and stocks accumulated by the company since there was no downtime in its operations during the crisis, we can assume that its revenue will grow by 10%. Assuming ALROSA’s additional emission will reach 25% of its authorized capital whereby the company will be able to reduce its net debt to $ 2.5 billion the company’s value after the IPO will be:
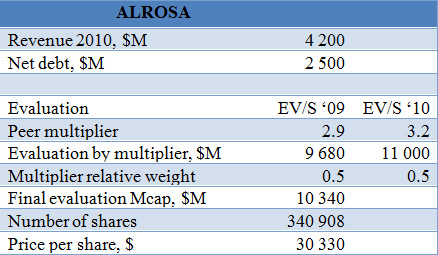
Source: AK ALROSA, Investkafe forecasts
Thus, the company's market value after the IPO should be $10.3 billion and one share after the capital increase will run at $30, 300.
In case of a public subscription at prices lower than those estimated, ALROSA is an eligible investment. It is most likely that before an IPO the company will split its stock to increase liquidity, which should attract individual investors.
