IFC Metropol has posted an update on its web portal written by company analysts Andrey Lobazov and Anna Antonova in regard of ALROSA’s equities put on the ‘buy’ list where the authors say:
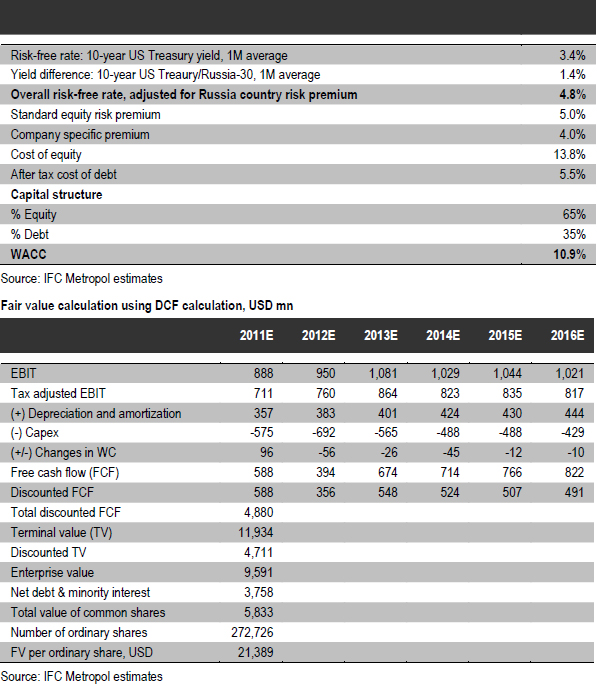
We increase our FV for ALROSA to USD 21,389 per share on new WACC estimates
We increase our fair value for ALROSA from USD 16,345 per share to USD 21,389 per share. Our new fair value implies 34% upside potential and we maintain our BUY recommendation on the stock. Our new FV implies capitalization of USD 5.7bn, which is lower than the preliminary IPO valuation of USD 8-10bn recently made by ALROSA President Fyodor Andreev.
We did not change our assumptions on production volumes and raw diamond prices, and the increase in FV was only due to an update of our WACC estimates.
WACC decreased from 12.8% to 10.9%, mainly due to a less aggressive company specific risk premium and lower cost of debt
We have revised our WACC calculation, applying a new 30-day average yield on T-bonds of 3.36% (previously 2.75%) and Russia-30 Eurobonds of 1.42% (previously 1.8%) to calculate the overall risk-free rate adjusted for Russia’s country risk premium.
We also reduced our company specific risk premium from 6% to 4%, or by 2ppts. We removed 1ppt from the risk premium as we now believe the company is successfully recovering from the crisis and its debt load has become less critical, reducing the risk to investors. We also removed another percentage point given notable improvements in transparency.
We have also revised our after-tax cost of debt estimate from 7.7% to 5.5% as of the company’s debt load has become noticeably lower. We used ALROSA Eurobonds (currently yielding 6.86% and maturing in 2020) as a basis for our assumption.
As the result, our WACC estimate decreased from 12.8% to 10.9%.
Debt load less critical and recovery is in line with our expectations
ALROSA’s recovery is in line with our expectations; 9M EBITDA increased by 140% y-o-y to RUB 30.1bn (USD 1bn) and accounts for 73% of our full-year forecast. Revenue totaled RUB 90.3bn (approx. USD 3bn) and accounts for 75% of our full-year estimate. As expected, ALROSA successfully restructured most of its expensive debt with new bond issues in 2010, and net debt decreased from USD 3.8bn to USD 3.2bn during 9M 10.
Considering 9M 10 financial results, we expect ALROSA to report full-year EBITDA in line with our estimates and forecast that net debt/EBITDA should decline from 6.3x in 2009 to 2.3x by FY 10. Easing the debt load should also lead to a reduction in the company’s specific risk premium.
Transparency has improved
ALROSA has said that by the end of 2011 it intends to meet all the requirements for a public offering, so it is not surprising to see substantial improvements in transparency.
ALROSA has started to publish quarterly IFRS figures and is emphasizing investor relations, regularly posting releases on the latest events and RAS/IFRS financial results. However, there is still room for improvement; the company does not yet publish regular operating results or disclose the size of reserves and resources.
In December 2010, the Yakut government voted to remove legal obstacles to an IPO - a big step toward a public offering
Until recently, a regional law stated that in the interests of Yakut government ALROSA must remain a closed joint stock company. However, on December 15, 2010 the Yakut legislature amended the law, allowing Alrosa to become an open JSC, provided that the Yakut government retains control of at least a 25% stake in the company in the case of any new share issue. This opens the way for an IPO.
On February 22, 2011, Alrosa is due to set the date for a general shareholder meeting to consider an IPO of 20% of outstanding shares for approx. USD 1.5-2bn, valuing the company at around USD 8-10bn.
Strategic investor for Severalmaz suggests new funds and technologies forthcoming
According to press reports, in late 2010 Alrosa agreed to sell a 50% minus one share stake in its Severalmaz subsidiary to Rio Tinto for USD 250mn. A BoD meeting was scheduled for December 28, 2010, to discuss the final approval of the deal. Although the final decision has yet to be disclosed, we believe that the sale was probably approved and will go through in the near future.
As a strategic investor, Rio Tinto would bring both necessary financing (USD 135mn to increase annual raw diamond production to 2mn carats by 2015) and new technologies to the project. These contributions would be valuable to Alrosa, as Severalmaz suffers from high production costs (at USD 70/carat while the sale price is close to USD 50/carat) and water intrusion problems at the mine site (Rio Tinto has experience in developing such deposits).
We believe the successful sale would allow ALROSA to increase future production capacity as well as improve operating efficiency for Severalmaz, which currently contributes a USD 33mn annual loss to the company’s financial results.
WACC Calculation