After the recent double-digit price increases by the major rough diamond suppliers, and the recoil by the market, it is now clear that the rough market has reached a saturation point, says Edahn Golan on IDEX Online.
More for Less
With the exception of Alrosa, most of the major diamond producers reported a decline in production. Despite planning an 8.5% increase in production, De Beers' production so far is flat (+0.6%) year-over-year.
According to IDEX Online estimates, global diamond production declined by about 3.7% in the first half of 2011 compared to the first half of 2010. The largest producers (Alrosa, De Beers, Rio Tinto, BHP Billiton, Harry Winston) mined nearly 44.4 million carats in the period, compared to ~46 million carats, the year before.
However while global production is declining, prices are racing ahead, rising some 40% to date. All the leading rough suppliers enjoyed a sharp rise in revenues in the first half of the year.
Just recently, De Beers increased prices by about 10%; Alrosa hiked prices by 20%-25%, another large rough diamond supplier of Angolan goods increased prices by 12%. The three are the bulk of the market's supply. These increases, taking place in July, are early indicators that the second half of the year will look as good for producers, if not better than the first half.
Hitting the Ceiling
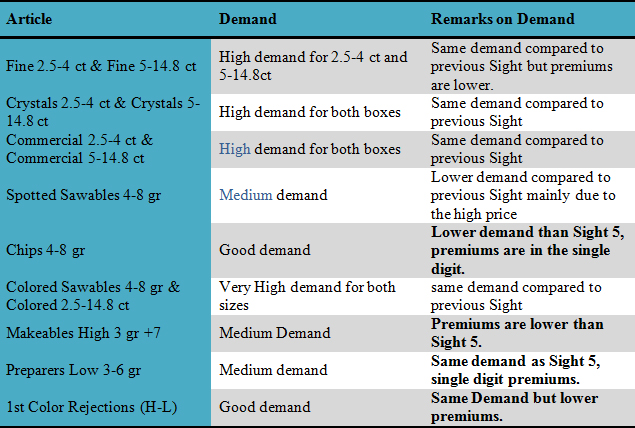
Not only that prices soared, the quantity unloaded on the market, mainly by the DTC, was massive. Maybe by design, the shock affect was immediate. Trading in DTC boxes was minimal and premiums shrunk considerably (see table below).
There are two more reasons for the slowdown in rough diamond trading. One is the halt in polished diamond prices. They are at record high levels, and all the indications are that 2011 will be a fantastic year in terms of consumer buying, however the season is a few months away and many traders are going on vacation. So while prices remain high, and sellers are unwilling to budge much because of the high rough and manufacturing costs, the wholesale buyers are not buying now.
One of the outcomes of this situation is an abundance of boxes in the market looking for buyers.
The second reason is financial, a shortage in cash, mostly in India. Indian manufacturers and rough traders are buying very selectively, mainly due to limited liquidity. When a buyer looks at a box – with the new price, plus premium - he sees a very pricy item in front of him. One manufacturer told IDEX Online that in September he will have to raise prices of polished just to protect his costs – not his margins.
Prices are now at a peak level and will likely remain there for a while without increasing further. In September – after the vacations end and when pre-season wholesale buying begins – manufacturers will have the ability to consider if they are able to pay more for their rough based on polished purchases.
H1 Bitter Sweet
Rough diamond supplies to the market in the fist six months of 2011 have exceeded $8.35 billion. This compared to about $6.25 billion worth of rough sold in the first half of 2010, or an increase of 33.6%. If prices remain at this level, 2011 rough supply to the market will near $17 billion.
The high prices are however just part of the story. The other part is lower production. After years of warnings that at some point diamond production will decline, it is happening. The good news is that consumer demand may have finally surpassed supply. The bad news is that the impact on the market is difficult to imagine at this stage.
Demand for Key DTC Boxes – Sight 6