As I noted earlier, the economic crisis has dramatically changed the pre-crisis balance between diamond mining, cutting and trading companies as competition between them in these conditions has sharply deteriorated. As a matter of fact, the third millennium, in which we have lived through quite a measurable part, is bringing about truly unprecedented transformations. If until recently there were four major companies, which played a primary role in the diamond industry, today the situation is changing rapidly and second-tier companies are beginning to come to the forefront. Therefore, to assess the prospects for the development of the world diamond mining segment, it turns out relevant to better define the place and role of companies in the future ranking within the diamond hierarchy on the basis of strategic analysis.
Such an analysis of their development prospects (Fig. 1) was performed using the classical model developed by the Boston Consulting Group (BCG) and improved by the author of this article, taking into account the changes in the production share and diamond output of the four leading companies (Table 1).
Table 1
Change in production share and growth in diamond output of the world's largest diamond mining companies in 2009-2012
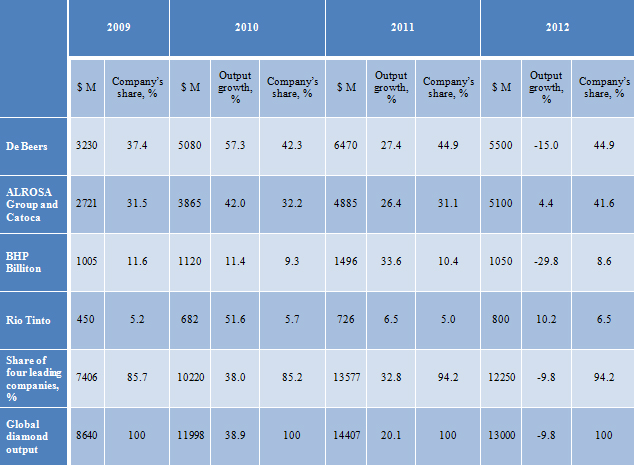 The table is compiled by the author based on the annual and quarterly reports released by De Beers, BHP Billiton, Rio Tinto, ALROSA and Catoca in 2008-2012.
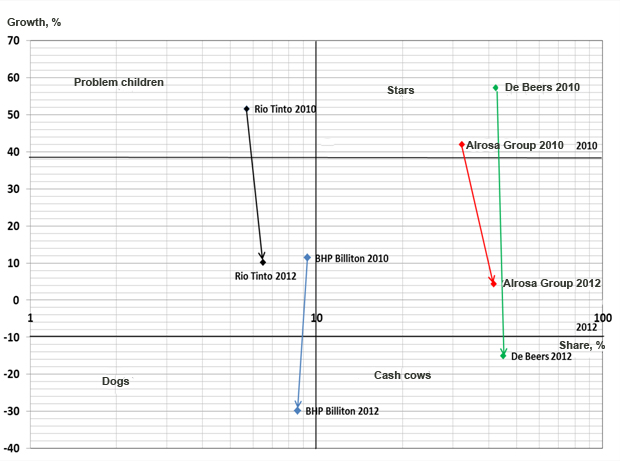
Fig. 1. The world's leading diamond mining companies in 2010-2012.
The matrix clearly shows the change in the companies’ position after the crisis and their prospects for the future. If in 2010 De Beers and ALROSA were in the "Stars" field, in 2012 only the Russian miner retained this position. De Beers moved into the "Cash Cow" category due to objectively lower performance of its business aggravated by the sale of the Oppenheimers’ diamond block of shares.
Rio Tinto and BHP Billiton were in the “Problem Children” position in 2010, but the latter slipped to the “Dogs” field in 2012. It is also understandable, especially because BHP Billiton has sold a part of its diamond assets (maybe viewed as non-core by this company) to a rapidly growing second-tier company, Harry Winston Diamond Mines Ltd.
In summary, it can be said that ALROSA Group has excellent prospects to establish hegemony in diamond mining. However, there is an alarming thing - many do not see this business as perspective and are getting rid of this risky, in their view, enterprise. It is likely that in the not too distant future the progress of science and technology can make it possible to grow large gem-quality synthetic diamonds in big quantities and at a much lower cost. Therefore in my opinion, it would be more correct to view the development of ALROSA as a diversified mining holding. All the more so that fortunately, the nature has not deprived Yakutia of mineral resources that can be extracted.
Yuri Danilov, Director of the Department of Subsoil Management Economics, Institute for Regional Economics of the North at Ammosov North-Eastern Federal University
