ALROSA has published some of the results for the 1st quarter of 2013, Pavel Emelyantsev says on the Investcafe portal. Thus, the company's revenue from diamond sales was $ 1.22 billion (about RUB 36.9 billion at the average exchange rate for the quarter), while its diamond output reached 7,480,000 carats. It means that the company’s production fell by 7.5% compared to the 1st quarter of 2012.
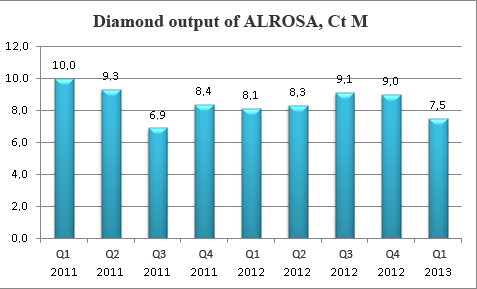
The diagram is built by Investkafe based on the company’s data.
However, ALROSA is keeping strict watch on its performance data and strives to improve the situation. In particular, the company has almost doubled its investments in new production facilities driving them to RUB 17.88 billion in 2012 from RUB 8.97 billion in 2011. That said, it should be noted that the miner’s capex went up 40% and hit RUB 30 billion.
In the 1st quarter of this year, ALROSA invested RUB 1.8 billion in the construction of three underground mines. So we can be sure that the company will maintain and enhance its position as the world's largest diamond miner in the years to come. However, we cannot forget about the not so positive general trend in diamond mining evident over the past years.
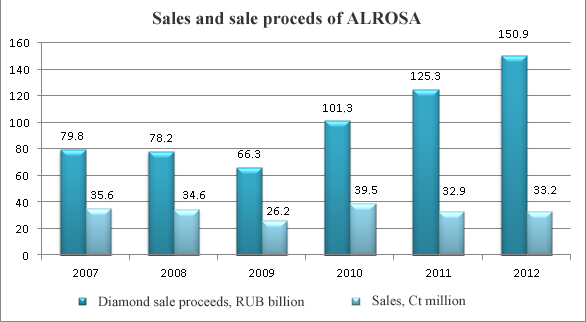
The diagram is built by Investkafe based on the company’s data.
The transition to underground mining will allow ALROSA to maintain a stable level of production, but will lead to an increase in the average cost.
It is noteworthy that the increase in capex inflated the company’s debt. Thus, ALROSA had a net debt of RUB 116.46 billion at the end of 2012, which is 39.4% higher than at the end of 2011 (RUB 83.54 billion). However, the debt burden remained within reasonable limits. The company’s Net Debt / EBITDA ratio was 1.88x versus 1.28x in 2011.
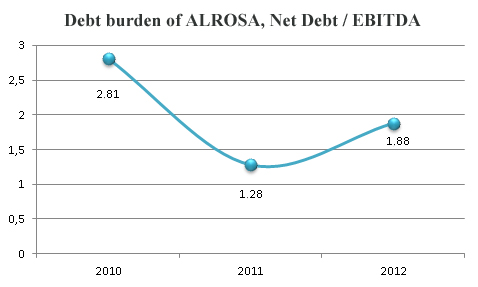
The diagram is built by Investkafe based on the company’s data.
I believe that ALROSA will continue to reduce its debt burden. It is worth noting that three quarters of its borrowings are long-term. In particular, the company needs to pay only RUB 8.4 billion this year and its major payments (more than RUB 60 billion) will be due in 2015. In my opinion, ALROSA’s lower Net Debt / EBITDA ratio and its management’s policy aimed at further reducing the debt could be more favored by investors at the upcoming public offering in November.
During the past months ALROSA’s shares were traded around the level of RUB 31.3 per share within a rather wide range. In my opinion, this level gives a pretty good potential with respect to the announced price range in the course of the autumn equity placement. Let me remind you that in view of this placement the miner’s shares were tentatively valued at RUB 39.5-45.5 per share.
Of course it is impossible to consider this kind of investment absolutely risk-free, but I believe that in this particular case the risk is justified. So my recommendation is BUY.
